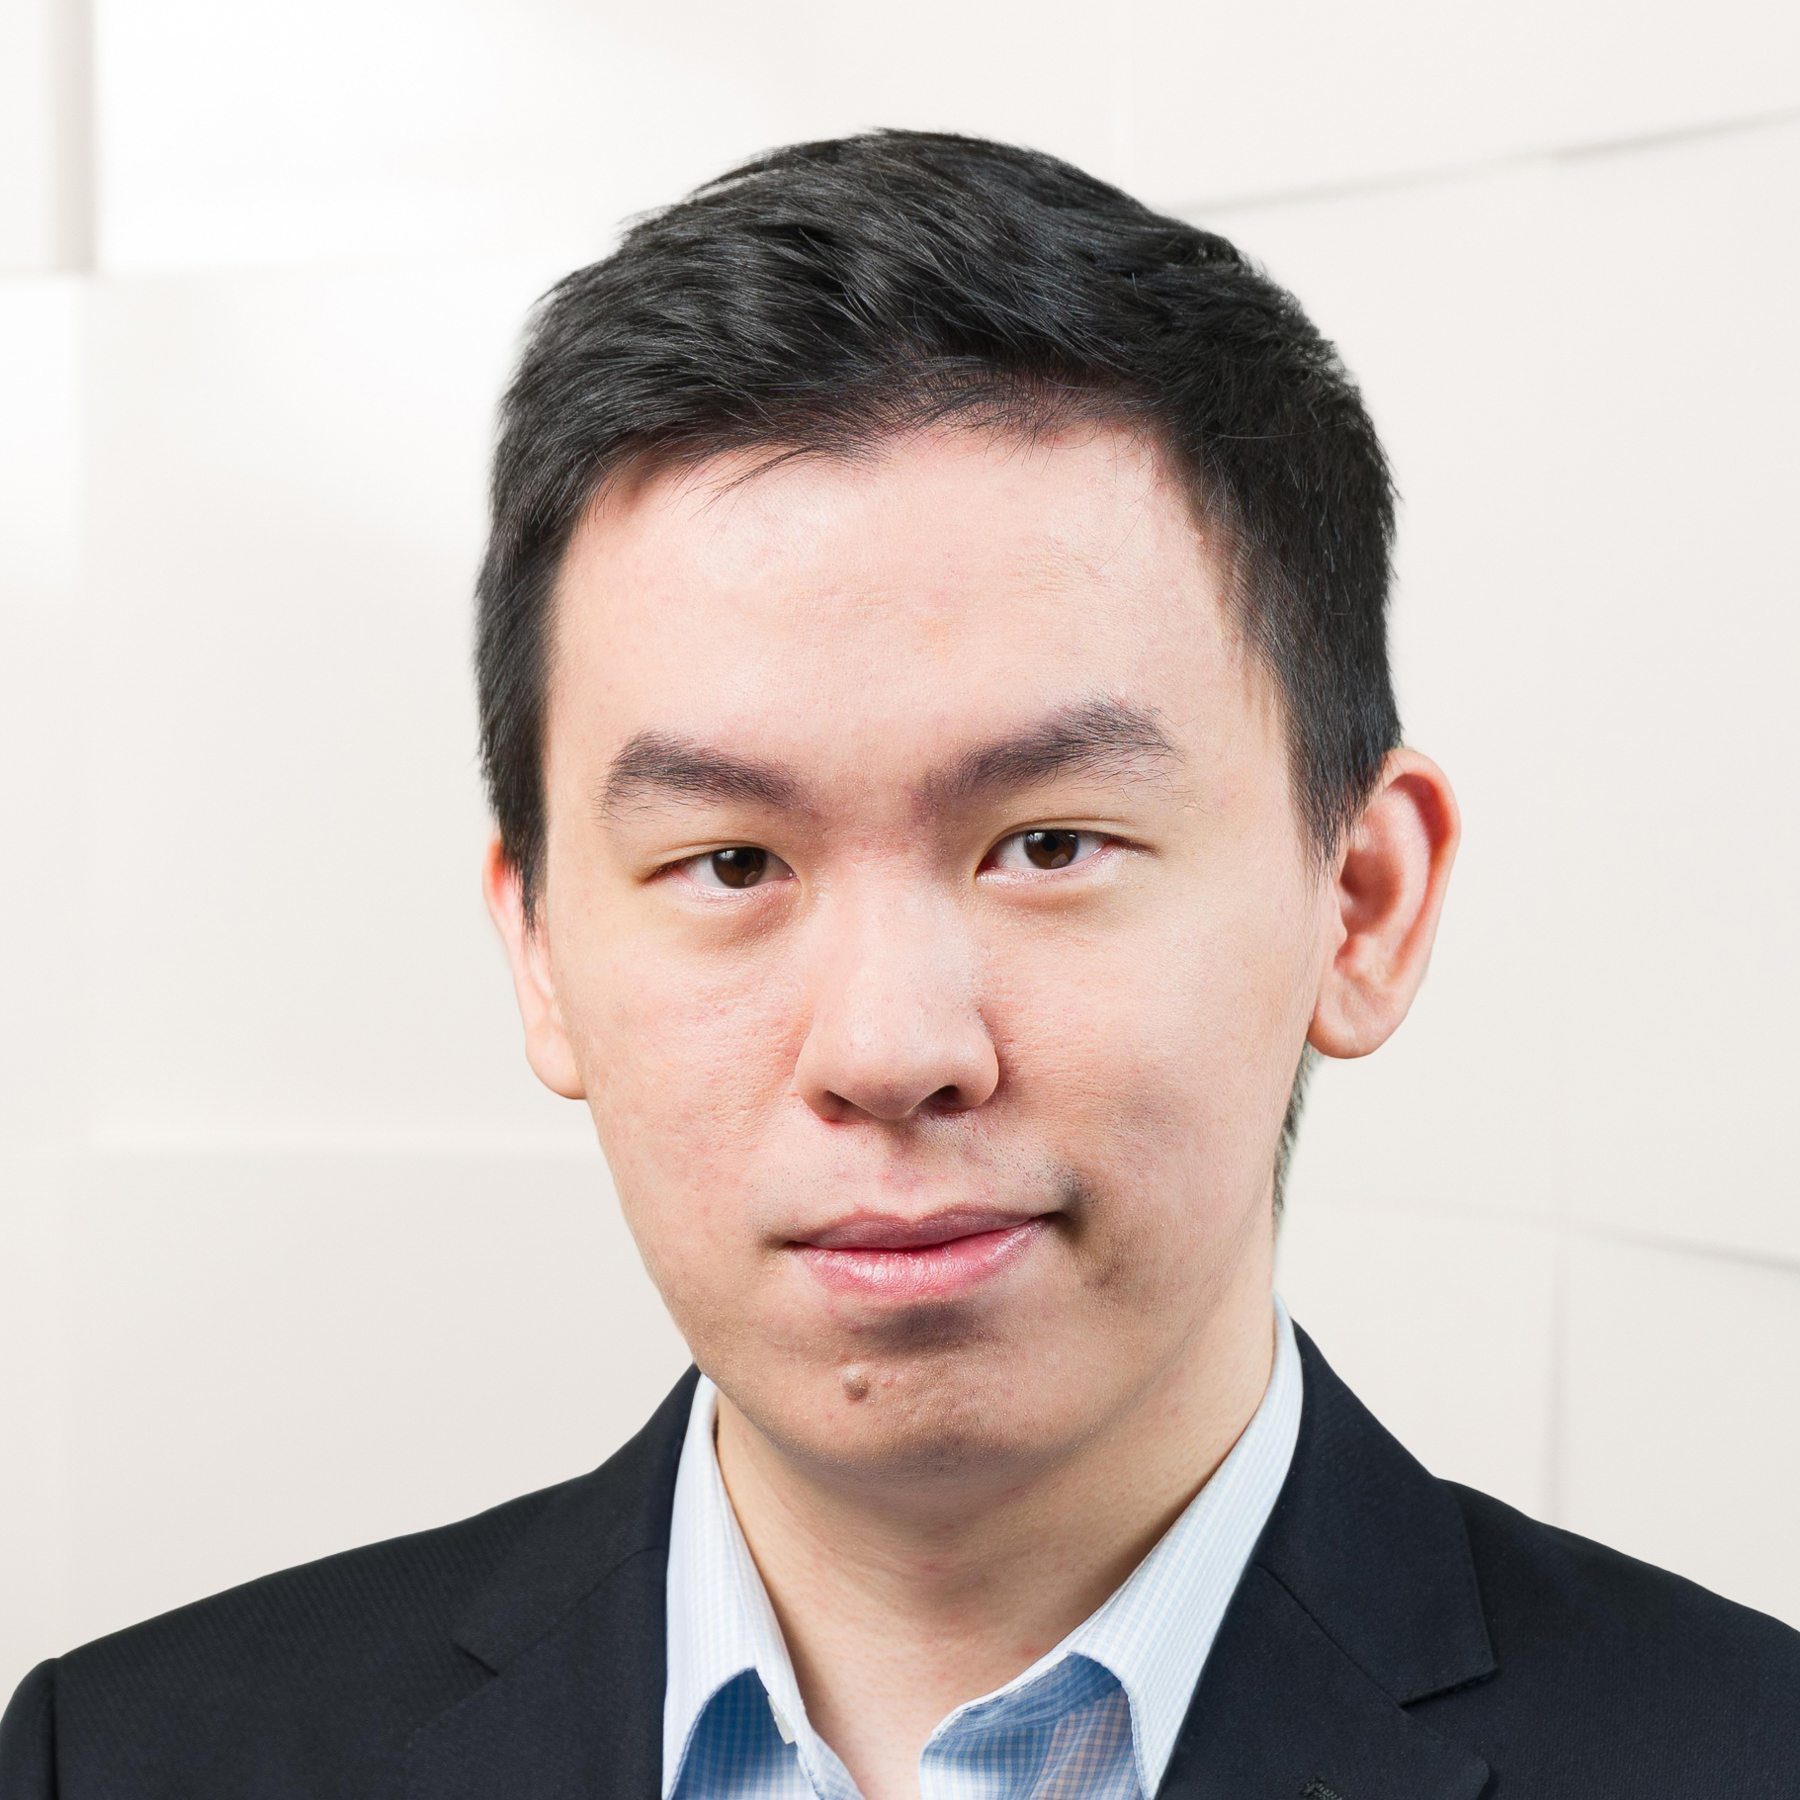
Dr Yanbin Xu
Lecturer
PhD in Finance with a specialisation in Actuarial Science, Nanyang Technological University, Singapore (2020-2024)
BSc (Hons, Highest Distinction) in Mathematical Sciences with a specialisation in Statistics and minors in Computing and Data Analysis and Finance, Nanyang Technological University, Singapore (2016-2020)
Financial Risk Manager (FRM), Global Association of Risk Professionals
Business School
School of Risk and Actuarial Studies
Yanbin Xu is a Lecturer in the School of Risk and Actuarial Studies at UNSW Business School. His research focuses on climate economy and sustainability issues within insurance and finance, with a particular emphasis on climate anomalies and natural hazards. Working in a multidisciplinary field, he develops quantitative models to assess and manage climate-related risks, with the broader aim of supporting more resilient and sustainable insurance systems. His work has been published in journals including Nature Climate Change, The Lancet Planetary Health, and Annals of Actuarial Science.
E-mail
- Publications
- Media
- Grants
- Awards
- Research Activities
- Engagement
- Teaching and Supervision
2024–2025: Co-PI, Society of Actuaries Research Grant, US$55,000 Project: Climate Anomalies and Their Enduring Impacts on the U.S. Mortality and Health Landscape (PI: Wenjun Zhu, Co-PI: Tianxiang Shi)
2022–2023: Co-PI, Casualty Actuarial Society CKER Individual Grant, US$18,000 Project: A Dynamic Updating Framework for Composite Models (PI: Wenjun Zhu, Co-PI: Ken Seng Tan)
2024: SCOR Actuarial Research Award, First runner-up
2020-2024: Insurance Risk and Finance Research Centre Graduate Scholarship
2018: Society of Actuaries Student Research Case Study Challenge Award, First runner-up
2016-2019: School of Physical and Mathematical Sciences Dean’s List
2016–2020: Nanyang Technological University Science Undergraduate Scholarship
2015–2016: Singapore SM2 Program Scholarship